
Options Pricing Monte Carlo
Price with simulations
Tenacious App Production, LLC
iPhone Screenshots


Description
Calculate option prices using simulations for power , European , and Heston models with stochastic volatility. Compute implied volatility and normal inverse using Beasley-Springer-Moro and Simpson methods.
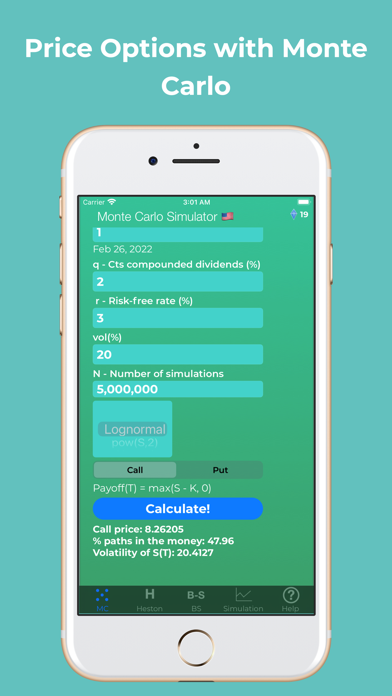
The Options Pricing Monte Carlo app prices power options: max(S^i -K,0) or max(K-S^i,0). It also shows the % of paths with positive payoffs. The normal inverse is calculated with Beasley-Springer-Moro method.
The Heston tab is used to price options under stochastic volatility using Monte Carlo.
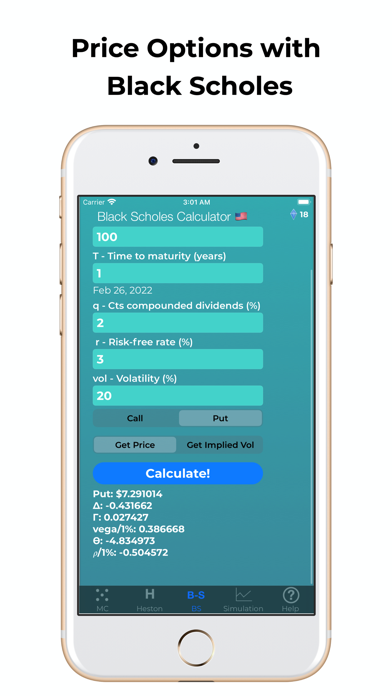
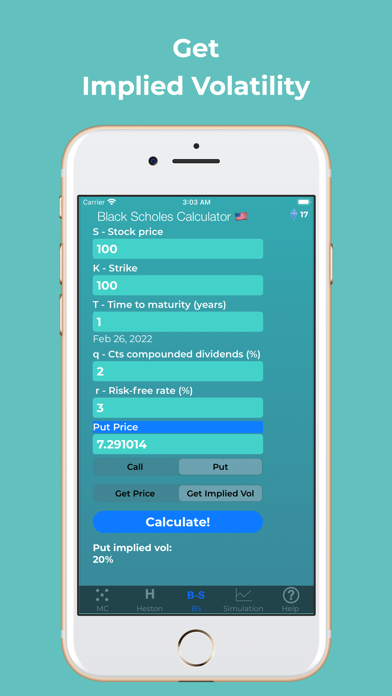
It also prices European options using Black-Scholes and can also calculate Implied Vol. Normal is calculated by direct integration using Simpson method with a low tolerance.
So 4 calculators in one:
- Monte Carlo simulator for regular European and Power options.
- Monte Carlo simulator for European options with stochastic vol (Heston model).
- Black Scholes calculator for price and greeks and implied vol.
- Simulation tab lets you visualize Brownian Motion with drift. (2D or vs time).